A limited company account should be compared using the business’s expected transactions, currencies and access requirements. Identify the provider and account structure before assessing protection claims. A convenient app is useful, but it does not explain every fee or responsibility associated with holding and moving company money.
The decision this article helps you make
Compare payment charges, cash handling, user permissions and accounting exports. Ask what information is needed during onboarding and how support would handle a blocked or disputed transaction.
Start with the transactions you actually expect
List the balance, spending or banking activity the product is intended to support. For a business account, include payment types, currencies, cash handling and the people who need access. For credit, identify expected repayment and any promotional period. A reward or introductory offer can be attractive without matching the way you will use the account after the initial period ends.
Convert the fee schedule into a realistic comparison
Ask about recurring charges, transaction fees, interest, transfers and services you may need occasionally. Check the conditions for a promotional benefit and what pricing applies when it ends. Use your expected activity to estimate relevant costs, labelling assumptions clearly. An account described as free may still charge for particular transactions, and a card with an annual fee may or may not justify that cost for your usage.
Understand the provider and the account structure
Identify the legal entity supplying the product and ask which account protections apply to that structure. Do not assume that every financial app operates as a bank or holds money in the same way. Verify relevant details independently and ask how access, fraud reporting and complaints would be handled. For business users, confirm permission controls and how access would be removed when an employee leaves.
Check the transition and the exit
Ask what happens when an introductory offer expires, an account is closed or a balance remains after a promotional period. If you are switching, identify payments and records that need attention before the previous arrangement ends. Save the pricing document and eligibility conditions. The final choice should suit normal use and a less favourable scenario, not simply the best possible interpretation of a bonus or rewards headline.
Compare the alternatives on the same basis
Choose the decision criteria before looking at promotional claims. Write down the outcome you need, the constraints you cannot change and the circumstances that would make an option unsuitable. Send the same basic requirements to each organisation. Otherwise, you may spend time comparing answers to different questions. A short comparison with clear assumptions is more useful than a long list of features that do not affect your decision.
Separate confirmed information from impressions. Written scope, disclosed charges and an identified delivery team belong in the first group. A persuasive conversation or an attractive website belongs in the second. Both can influence your experience, but they should not carry the same weight. Where an answer is missing, leave a visible gap rather than filling it with an optimistic assumption. Ask a follow-up question that could resolve the uncertainty.
Finally, test your preferred option against a plausible difficulty: a delay, a change in scope, an unavailable contact or an unexpected additional cost. Ask how the agreement would handle that situation. This can reveal important differences that a simple price ranking hides. Choose the option whose commitments and limitations you understand, and record why it fits your needs. If the essential information is still missing, improve the comparison before treating the shortlist as a final decision.
Apply the comparison to your location
UK-wide marketing can conceal differences between the services available in England, Wales, Scotland and Northern Ireland. Identify the nation relevant to your circumstances and ask the provider to explain any local limitations. Where regulation applies, check the appropriate register and the firm’s contact details independently. Registration is a starting check, not a promise of a particular outcome. Ask whether the quoted amount includes VAT where applicable, which organisation would take your payment and which complaints process applies to that specific service.
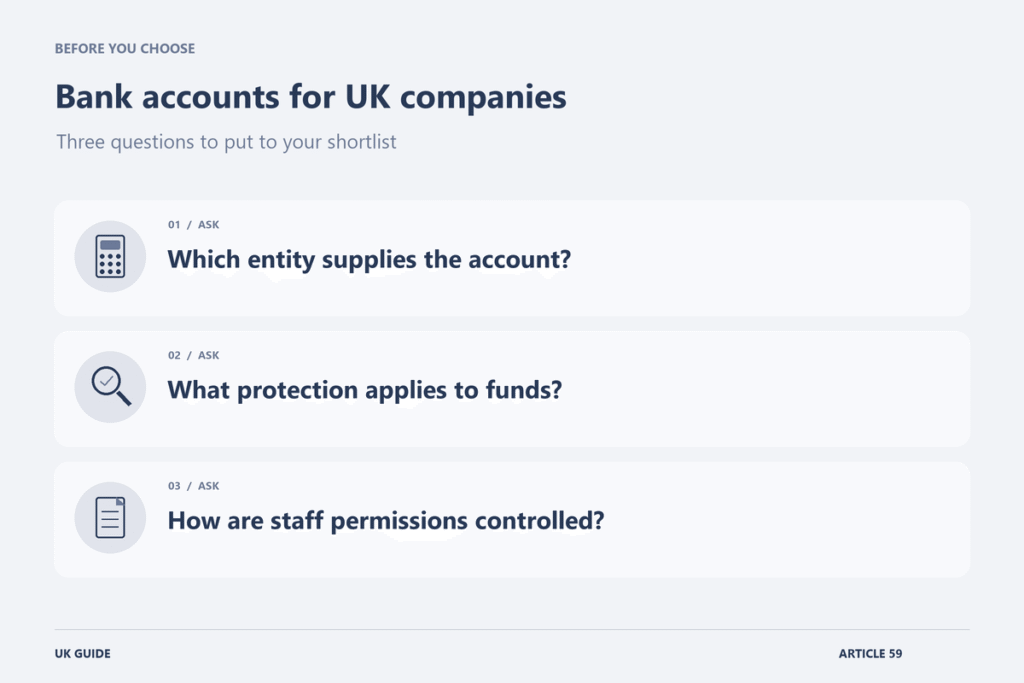
Questions to put to your shortlist
- Which entity supplies the account?
- What protection applies to funds?
- How are staff permissions controlled?
A point that is easy to miss
Bank accounts and other payment accounts may hold funds under different arrangements. Check the specific provider’s status and protection explanation rather than relying on the word account.
Put the comparison into practice
List the payments and records the company needs: supplier transfers, customer receipts, currencies, cash deposits and bookkeeping exports. Ask providers to show the actual charges for that pattern, including any limits or separately priced functions. A free subscription tier may still be unsuitable if routine business activity creates repeated additional charges.
Identify the legal entity operating the account and read its explanation of how customer money is held and protected. Check relevant status independently rather than inferring it from the app design or the word bank in informal marketing. Ask how a director would recover access, remove a former employee’s permissions or raise an urgent payment query. Those operational questions make the comparison more useful than a long list of features the company may never use.
Make the final decision from the written offer
Request a proposal that reflects the circumstances you actually discussed. Check the name of the contracting organisation, the work included, the charging basis and the person responsible for answering questions. Resolve any important difference between the conversation and the documents before proceeding. Keep a dated copy of the version you accept. If an essential assumption remains uncertain, ask what evidence would settle it and how that uncertainty could affect your next step.
Further reading
Related reading
- Balance Transfer Credit Cards: Comparing Transfer Fees and Promotional Periods (UK)
- Business Checking Accounts: Comparing Fees, Bonuses and Cash Deposit Limits (USA)
- Balance Transfer Credit Cards: Comparing Fees and Promotional Offers (USA)
- Business Credit Cards: Comparing Rewards, Annual Fees and APRs (USA)
Explore more in Credit and Banking.